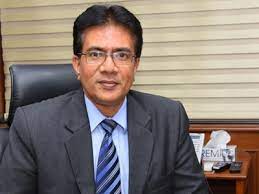
Yes Bank managing director and CEO Vinay M Tonse could hardly rejoice at the lender’s second-quarter performance, which beat market estimates to post a 65% year-on-year rise in net profit to Rs 1,080 crore.
There is another figure that Tonse disturbingly stared at: a quarterly net loss of Rs 5,217 crore, if the Supreme Court’s ruling on additional tier-1 (AT1) bonds prevailed.
Yes Bank’s board got into a prolonged meeting and a media conference call, scheduled for Saturday afternoon, was postponed. Tonse and his senior team were preparing to explore “all legal remedies available”, including filing a review petition in the SC, as the financial figures reported in the fiscal second-quarter ended September would look dismal if they were adjusted to reflect the court ruling.
The performance reversal would spread to also the bank’s net worth, borrowings and common equity tier-1 (CET1). The net worth would slide to Rs 46,970 crore from Rs 53,268 crore reported in Q2; the borrowings would rise to Rs 86,149 crore from Rs 77,734 crore; the CET1 ratio decline to 11.4% from 13.7%; and return on assets (RoA) turn negative 4.3% from 0.9% declared in the September quarter.
The gravity of the situation centred around a ruling by the apex court this week that set aside the bank’s write-off of Rs 8,415 crore of AT1 bonds. The SC upheld a 2023 Bombay High Court judgment on the write-down matter and dismissed appeals filed by the bank.
“We are examining it (the SC order) in detail and will take appropriate steps in accordance with the applicable legal and regulatory requirements. We will keep our stakeholders informed as matters progress. The bank remains firmly focused on sustaining the strength and growth of its franchise, while continuing to provide our customers with consistent service and support across their banking requirements,” Tonse, former managing director at State Bank of India, said.
Yes Bank clarified it is “yet to complete its assessment and determination of the implications” and “no impact arising from the judgment has been recognised in the reported Q2FY27 financial results”.
The reported figures were indicative and subject to revision as the bank assessed the implications of the ruling.
“The pro forma estimates are subject to revision based on the consequential actions, further legal assessment and final accounting and regulatory treatment,” the lender said.
In a regulatory filing, the bank, which is 24.9% owned by Japan's Sumitomo Mitsui Banking Corporation (SMBC), said it is presently “evaluating the consequential implications of the judgment, including the decisions and actions required to give effect to it, the manner and timing of implementation and the resulting financial and accounting implications”.
The bank is also evaluating, in consultation with its legal advisers, all legal remedies available to it, including such further proceedings as may be maintainable before the SC.
“Pending completion of this assessment and determination of the appropriate accounting treatment, no impact arising from the judgment has been recognised in the reported Q2FY27 financial results and half-year ended 30 September 2026,” the lender said.
“Any consequential financial impact including regulatory and financial ratio will be recognised in accordance with the applicable accounting requirements, having regard to the determination of such consequential matters and further legal developments, as applicable,” it added.
Financial impact during H1 of FY27
The bank’s net profit of Rs 2,151 crore reported for the first half of the current financial year would sink to a net loss of Rs 4,146 crore if the figures were adjusted to reflect the apex court ruling.
Similarly, the average RoA would slip to 1.7% on an annualised basis.
The capital adequacy ratio, however, would remain the same at 14.5%, the bank said.
Supreme Court’s ruling
The SC bench of Justices Dipankar Datta and Augustine George Masih, in its judgment on 15 October 2026, upheld the Bombay HC verdict dated 20 January 2023 and dismissed the appeals filed by the bank, the Administrator, the Reserve Bank of India and the Union government.
The court ruled that the bank administrator lacked the legal authority to write off the AT1 bonds on 14 March 2020. The power to do so rested with the RBI and the final reconstruction scheme contained no specific provision for it.
The court criticised the RBI for being a “mere bystander” that allowed Yes Bank’s CET1 ratio to drop to an astonishing low of 0.6% while operations were conducted improperly.
“It cannot be denied that material irregularities in the functioning of Yes Bank were noticed much prior; criminal prosecution has also been initiated against the personnel of Yes Bank. However, to have the investors at the receiving end of the administrative lapses would be highly unfair," the bench said.
The court ruled that annual coupon payments and bond terms remain unaffected per the information memoranda.
Yes Bank had to thus honor the restoration/repayment of the Rs 8,415 crore principal and accumulated interest to bondholders.
Since the 15 October order, Yes Bank's shares have fallen more than 17% on the stock exchanges.
What are AT1 bonds
AT1 bonds are a type of perpetual debt instrument issued by banks to strengthen their core capital base. They do not have a maturity date but the bank can buy them back via a call option.
If the bank's core capital falls dangerously low, these bonds can be converted into equity shares or written off entirely.
Since they carry higher risk, banks offer higher coupon rates.
Why had Yes Bank issued AT1 bonds
As part of a capital raising exercise to fund aggressive loan growth and strengthen its core regulatory capital, Yes Bank issued AT1 bonds in two tranches.
On 23 December 2016, the private lender issued AT1 bonds worth Rs 3,000 crore with a coupon rate of 9.5%. Again, on 18 October 2017, the bank issued Rs 5,415 crore of AT1 bonds with a coupon rate of 9%, taking the total issuance to Rs 8,415 crore.
During these years, the bank was rapidly expanding its corporate loan book. These chunky loans were extended to a few large corporate houses and in sectors like real estate, power and infrastructure. Eventually, the loans turned toxic and the bank plunged into a crisis.
The Supreme Court noted that Yes Bank had actively mis-sold and aggressively pushed the AT1 bonds as “super fixed deposits” to unaware retail individual investors in violation of standard RBI guidelines.
What led to the collapse of Yes Bank
Founded in 2004 by Rana Kapoor and Ashok Kapur, Yes Bank grew rapidly on the back of corporate loans and became India’s fourth-largest private sector bank.
The loan book expanded from Rs 55,633 crore to over Rs 2.25 lakh crore between 2014 and 2019.
The bank, however, accumulated over Rs 51,000 crore in bad loans and had heavy exposures to Anil Ambani-led Reliance Group, Essel (Zee) group, Dewan Housing Finance Corporation Ltd (DHFL), Infrastructure Leasing & Financial Services (IL&FS) and Jet Airways. The collapse of these companies added to the woes of Yes Bank.
The RBI also discovered loan divergences and under-reporting of non-performing assets (NPAs). Picking up the stick, the regulator did not extend Kapoor’s term as MD and CEO beyond 31 January 2019.
The bank faced a terminal liquidity run in March 2020, triggering the RBI to supersede the board and appoint an administrator. The withdrawal limit was capped at Rs 50,000 per depositor to prevent a run on the bank.
The RBI then drafted a reconstruction scheme and got a clutch of banks, led by SBI, to infuse capital and rescue Yes Bank. Prashant Kumar, the chief financial officer of SBI, was appointed first as adminstrator and later, in the same month, as MD and CEO of the bank.
On 14 March, the administrator ordered the permanent write-off of all Yes Bank’s AT1 bonds. Mutual funds and retail investors legally challenged the decision, stating that the administrator had overstepped his boundaries because the final reconstruction scheme did not mention of a write-down.
What did the Bombay HC rule
On 20 January 2023, the Bombay High Court ruled in favour of the bondholders and quashed Yes Bank’s decision to write off the bonds.
The court noted that the administrator did not have the authority to take such a decision and it rested strictly with the RBI.
The HC, however, kept its own order in abeyance for six weeks to allow Yes Bank a fair window to appeal against it in the apex court without having to immediately restore Rs 8,415 crore onto the balance sheet.
The matter moved to the SC in March 2023 and the stay was extended while it reviewed the appeals on merit. The status quo remained for over three years until on 15 October 2026, the SC dismissed the bank’s appeals and vacated the stay.
Q2 results
The bank’s operating profit rose 29.4% YoY to Rs 1,678 crore for the quarter ended September 2026.
Net interest income rose 22.7% YoY to Rs 2,822 crore, while net interest margin (NIM) declined to 2.6% from 2.7% in the previous three months.
The gross NPA ratio improved to 1.2% at the end of September, from 1.3% in the previous three months and 1.6% a year ago.
Net NPA ratio was at 0.2%, same as in the previous three months. In the year-ago period, it was at 0.3%.
The loan book crossed the milestone of Rs 3 lakh crore and ended the September quarter at Rs 3.10 lakh crore, up 23.7% YoY.
Deposits grew 19.5% YoY to Rs 3.54 lakh crore as on 30 September 2026.
The CASA (current account savings account) share in the total deposits mix declined to 30% as on 30 September, from 32.7% in the previous quarter and 33.7% a year earlier.
The bank mobilised Rs 18,575 crore ($1.94 billion) in foreign currency non-resident (Bank), or FCNR(B), deposits under the RBI’s concessional swap window.
The bank said it is evaluating options to strengthen its capital buffers to support growth.